Second Quarter Health Insurance Segment Profitability Trends
October 28, 2026
In this brief, Mark Farrah Associates (MFA) compared results through the second quarter, year-over-year (YOY) profitability for the Individual, Employer-Group, Medicare Advantage, and managed Medicaid health insurance segments. Financial insights were gleaned from aggregated 2Q25 and 2Q26 statutory financial data from MFA’s Health Coverage Portal™.
Individual Segment Performance
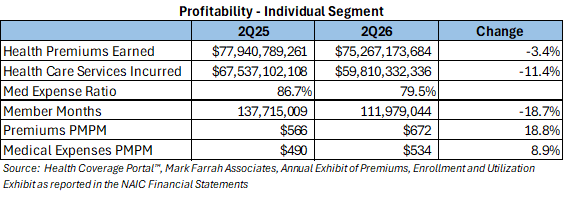
According to financial statements filed with the National Association of Insurance Commissioners (NAIC) and estimates from Mark Farrah Associates, enrollment in individual medical plans declined to approximately 21.9 million members as of June 2026, down from 26.5 million in June 2025. The reduction of more than 4.5 million covered lives was largely attributable to the expiration of enhanced public health exchange subsidies at the end of 2025.
Despite the enrollment decline, the individual market demonstrated improved underwriting performance during the first half of 2026. Premiums earned decreased 3.4% year-over-year (YOY), while medical expenses incurred fell 11.4% compared to the first half of 2025. On a per member per month (PMPM) basis, which accounts for changes in membership reporting plan premiums increased 18.8%, reflecting higher revenue per enrollee, while medical expenses rose a more moderate 8.9%.
For the first half of 2026, the average medical expense ratio (MER) for the individual segment declined to 79.5%, compared with 86.7% during the same period in 2025, indicating that medical cost growth remained well below premium growth despite the contraction in enrollment.
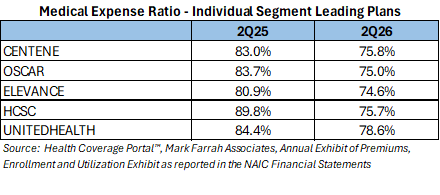
Overall, all five leading Individual market insurers reported lower medical expense ratios in 2026, reflecting stronger margin performance compared with the prior year period. HCSC posted the largest decline, with its MER falling 14.1 percentage points from 89.8% through 2Q25 to 75.7% through 2Q26. Elevance recorded a 6.3 percentage point decline, decreasing from 80.9% to 74.6%, the lowest ratio among the top five plans in 2Q26. UnitedHealth reported the smallest YOY improvement, with its ratio declining 5.8 percentage points from 84.4% to 78.6%. It is interesting to note that these early results for 2026 are more in line with the similar period in 2024 than with last year. (1).
Employer-Group Segment Performance
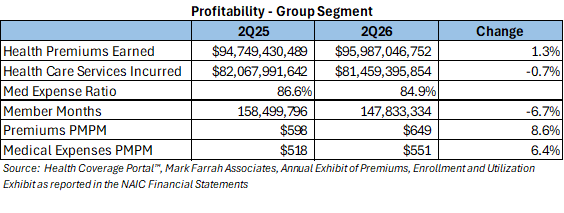
Health insurers operating in the Employer Group risk segment reported 40.4 million members as of June 30, 2026, representing a 4.4% decline from the prior year. Despite the membership decrease, financial performance showed modest improvement. Through the second quarter of 2026, premiums earned increased 1.3% compared to results at the end of 2Q25, while medical expenses declined 0.7%.
On a per member per month (PMPM) basis, premiums earned rose 8.6% YOY, compared with a 6.4% increase in medical expenses. The stronger growth in premium revenue relative to medical costs contributed to improved operating results, with the segment's average medical expense ratio (MER) decreasing to 84.9% through 2Q26 from 86.6% through 2Q25.
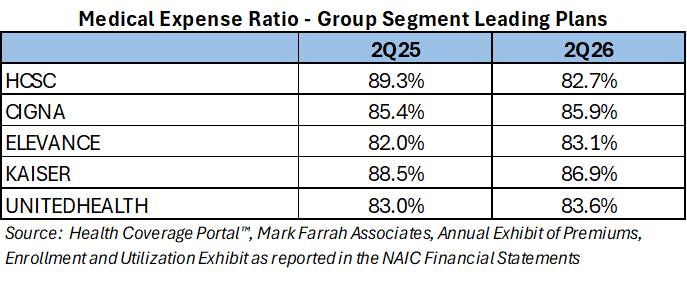
The top five Employer Group market leaders reported mixed YOY medical expense ratio trends through the second quarter of 2026. As it did in the Individual market, HCSC recorded the most significant improvement, among its peers in the Employer Group market, with its medical expense ratio MER decrease, of declining 6.6 percentage points, from 89.3% though 2Q25 to 82.7% through 2Q26. Kaiser also reported improved performance, with its ratio decreasing 1.6 percentage points. In contrast, Elevance, UnitedHealth, and Cigna each posted slightly higher medical expense ratios compared to the prior year.
Medicare Advantage Performance
Medicare Advantage (MA) segment growth is continuing, but at a slower rate compared with previous years. According to CMS Medicare Advantage enrollment reports aggregated by MFA in Medicare Business Online™, total Medicare Advantage plan enrollment was approximately 35.1 million as of June 1, 2026: a growth of almost 700,000 members or 2.0% since June 1, 2025.
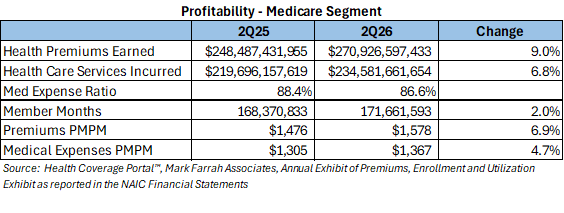
Medicare insurers reported improved YOY growth for the first half of 2026, driven by increases in both enrollment and premium revenue. Health Premiums Earned rose 9.0% to $270.9 billion, outpacing the 6.8% increase in Health Care Services Incurred, which reached $234.6 billion. On a per-member basis, Premiums PMPM increased 6.9% to $1,578, while Medical Expenses PMPM grew at a more moderate 4.7% to $1,367. As a result, the MER improved from 88.4% through 2Q25 to 86.6% through 2Q26, contributing to improved underwriting performance for the industry.
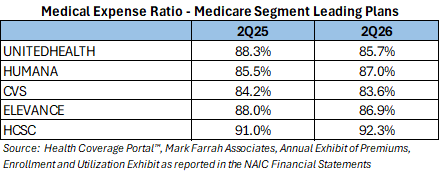
Turning our attention to the segment leaders, three of the five Medicare plans reported improved MER YOY. UnitedHealth improved its MER from 88.3% to 85.7%, a decline of 2.6 percentage points. Elevance also reported stronger results, lowering its MER from 88.0% to 86.9%, reflecting better medical cost performance compared to premium revenue. In contrast, HCSC reported the highest ratio among the leading plans and the largest YOY increase, climbing from 91.0% to 92.3%. Despite the mixed results, all five leading Medicare insurers reported MERs within a range of 83.6% to 92.3% in 2Q26, highlighting ongoing pressure from medical cost trends while demonstrating varying levels of success in managing utilization and healthcare expenses.
Managed Medicaid Performance
Centers for Medicare & Medicaid Services (CMS) reported Medicaid and CHIP membership of almost 73.2 million for June 2026, down from 77.7 million members in June 2025.
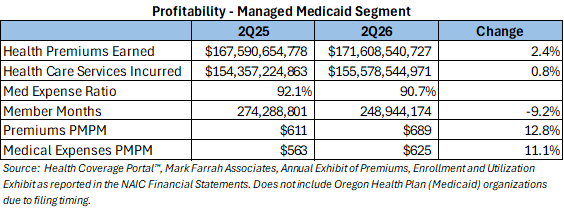
Health Premiums Earned increased 2.4% to $171.6 billion, while medical expenses incurred grew just 0.8% to $155.6 billion. On a PMPM basis, premium earned increased by 12.8% to $689 while medical expenses increased 11.1% to $625. Because premium growth outpaced medical cost growth, the MER improved from 92.1% in 2Q25 to 90.7% in 2Q26.
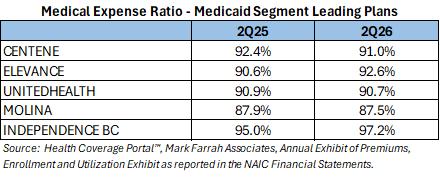
The five largest Medicaid insurers reported mixed results through the second quarter of 2026. Centene, Molina, and United reduced their MERs by 1.4, 0.4, and 0.2 percentage points, respectively. In contrast, Elevance experienced a deterioration in performance, with its MER increasing 2.0 percentage points, reflecting higher medical costs compared to premium revenue. Independence Blue Cross (BC) continued reporting both the highest MER among the leading plans and the largest YOY increase, rising from 95.0% to 97.2%.
Conclusion
On a consolidated level, through the second quarter of 2026, health plans are reporting net underwriting gains of 3.8%, compared to 1.5% last year at this time, driven by improved medical expense ratios, significant net reinsurance recoveries and changes to reserve levels. This improvement comes after a particularly challenging 2025, when many payers faced significant pressure from elevated healthcare utilization and rising medical expenses. As profitability trends continue to evolve, Mark Farrah Associates (MFA) will monitor and report on key developments across health insurance market segments. Stay tuned for future analysis briefs providing valuable insights into industry performance and emerging healthcare trends.
About Our Analysis
Medical expense ratio is calculated by dividing year-to-date health care costs/claims incurred by year-to-date premiums earned, for the six-months ended June 30. This ratio indicates the amount of premium dollars spent on medical expenses. The higher the ratio, the less room there is for the plan to pay for its administrative costs, potentially impacting profitability. Per member per month (PMPM) calculations are also used to determine the amount of premium dollars earned and the amount of medical costs incurred for each member on a monthly basis. These calculations are performed by dividing premiums or medical claims incurred by the number of reported member months for the plan.
Data for this analysis was sourced from Mark Farrah Associates’ Health Coverage Portal™, Quarterly Exhibit of Premiums, Enrollment & Utilization (EPEU) as reported in the NAIC Financial Statements and the NAIC Statement of Revenue and Expenses. Approximately 80% of the health insurance market is represented within the exhibit. Managed Medicaid plans & California HMO plans that do not report to the NAIC, along with NAIC-reporting Life, Accident & Health, and Property & Fraternal Insurance plans do not file the exhibit. To improve the accuracy of our assessment, premiums earned and member month data was estimated based upon the NAIC Statement of Revenue and Expenses due to incomplete or erroneous EPEU reporting by a small number of plans.
About Mark Farrah Associates (MFA)
Mark Farrah Associates (MFA) is a leading data aggregator and publisher providing health plan market data and analysis tools for the healthcare industry. Our product portfolio includes Health Coverage Portal™, County Health Coverage™, 5500 Employer Health plus, ASO Employer Health plus, Medicare Business Online™, Medicare Benefits Analyzer™, and Health Plans USA™. For more information about these products, refer to the product pages and brochures available under the Our Products section of the website (www.markfarrah.com) or call 724-338-4100.
Healthcare Business Strategy is a FREE brief that presents analysis of important issues and developments affecting healthcare business today. If you would like to be added to our email distribution list, please submit your email to the "Subscribe to MFA Briefs" section at the bottom of this page.